In the complex landscape of wealth management, estate taxes have long been a pivotal consideration for high-net-worth individuals and their heirs. As governments worldwide grapple with fiscal challenges, estate taxes serve as both a revenue-generating tool and a means of addressing wealth inequality. This dual purpose, however, places significant pressure on those engaged in high-value inheritance planning. Navigating the intricacies of estate taxes requires a strategic approach, as the implications can extend far beyond mere financial calculations, influencing decisions on asset distribution, philanthropic endeavors, and even family dynamics. This article delves into the profound impact of estate taxes on high-value inheritance planning, dissecting the challenges and opportunities they present and exploring strategies to optimize wealth transfer while minimizing tax liabilities. Through an analytical lens, we will examine current trends, legal frameworks, and innovative solutions that are shaping the future of inheritance planning in the face of evolving tax landscapes.
Understanding the Complexities of Estate Taxes in High Value Inheritances
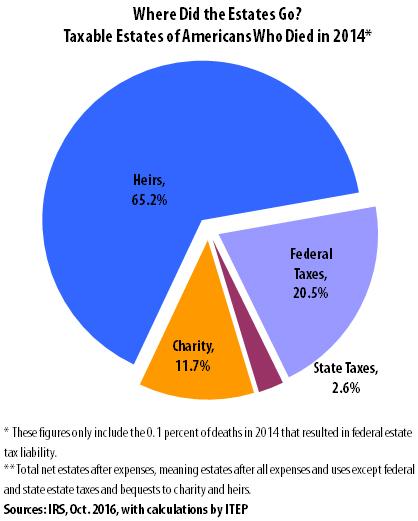
Navigating the intricacies of estate taxes in the realm of high-value inheritances requires an astute understanding of both federal and state tax laws. Estate taxes can significantly impact the net value of an inheritance, with potential liabilities reaching into the millions. For estates exceeding the federal exemption threshold, which is subject to change based on legislative adjustments, the tax rate can be as high as 40%. Moreover, many states impose their own estate or inheritance taxes, each with varying exemption limits and tax rates. This multifaceted landscape necessitates strategic planning to minimize tax liabilities and preserve wealth across generations.
Key strategies to mitigate estate taxes often include:
– Establishing trusts: Various types of trusts can be utilized to reduce taxable estate value, providing tax-efficient wealth transfer mechanisms.
- Lifetime gifting: Taking advantage of annual gift tax exclusions and lifetime exemption limits can help reduce the taxable estate.
– Charitable contributions: Donating to qualified charities not only supports philanthropic goals but also offers significant tax deductions.
- Utilizing family-owned business deductions: Special provisions exist for family businesses that can substantially lower estate taxes.
By employing these strategies, individuals can effectively navigate the complex terrain of estate taxes, ensuring that their wealth is optimally preserved for future generations.
Analyzing the Economic Implications of Estate Taxes on Wealth Transfer
Estate taxes, often dubbed the “death tax,” can significantly influence the strategies employed in high-value inheritance planning. When considering the transfer of wealth across generations, the implications of these taxes become paramount. High-net-worth individuals must navigate a labyrinth of regulations that can drastically alter the intended distribution of assets. The challenge lies in minimizing the tax burden while ensuring that the legacy aligns with the benefactor’s wishes. Strategies such as gifting, establishing trusts, and charitable donations are frequently employed to mitigate potential tax liabilities. However, these approaches require careful planning and expert legal guidance to ensure compliance and effectiveness.
- Gifting: Allows for the transfer of wealth without immediate tax implications, though it must adhere to annual exclusion limits.
- Trusts: Offer a way to manage and protect assets, providing flexibility and control over the timing and conditions of the transfer.
- Charitable donations: Can reduce the taxable estate value while fulfilling philanthropic goals.
The ripple effect of estate taxes extends beyond individual wealth; it impacts the economy by influencing investment decisions and the allocation of resources. As such, it is crucial for policymakers and stakeholders to consider these implications when contemplating reforms or adjustments to current estate tax laws. The interplay between tax policy and wealth transfer underscores the need for informed, strategic planning to safeguard financial legacies while contributing to economic stability.
Strategies for Mitigating Estate Tax Liabilities in Inheritance Planning
To effectively navigate the complexities of estate taxes, it’s crucial to implement well-considered strategies. One approach is leveraging gifting strategies. By systematically gifting assets during your lifetime, you can reduce the size of the taxable estate. This not only diminishes the potential estate tax burden but also allows heirs to benefit from the assets sooner. Another effective tactic is establishing irrevocable trusts. These trusts can remove assets from your estate, thus lowering taxable value while still allowing control over the distribution of those assets.
- Family Limited Partnerships (FLPs): By transferring business interests to an FLP, you can retain control while gradually gifting limited partnership interests to heirs, thus reducing the taxable estate.
- Charitable Contributions: Making significant charitable donations can both benefit society and reduce estate size, qualifying for charitable deductions.
- Life Insurance Trusts: An irrevocable life insurance trust can ensure that the proceeds from life insurance policies are not included in the taxable estate, providing liquidity to pay estate taxes.
Implementing these strategies requires careful planning and expert advice to ensure compliance with tax laws and to optimize benefits. By proactively addressing estate tax liabilities, you can safeguard your wealth and ensure a smoother transition for your heirs.
Expert Recommendations for Optimizing High Value Estate Planning
In the realm of estate planning, particularly for high-value estates, navigating the intricacies of estate taxes is paramount. Expert strategies focus on minimizing tax liabilities while ensuring the seamless transfer of wealth. Key recommendations include:
- Utilizing Trusts: Establishing irrevocable trusts can effectively remove assets from your taxable estate, offering both asset protection and tax advantages.
- Gifting Strategies: Implementing a gifting strategy during your lifetime can significantly reduce the taxable estate value, taking advantage of annual gift tax exclusions and lifetime exemptions.
- Charitable Contributions: Incorporating charitable donations not only fulfills philanthropic goals but also provides significant tax deductions, thereby reducing the overall taxable estate.
Moreover, periodic reviews of your estate plan are crucial to adapt to changing tax laws and personal circumstances. Engaging with a seasoned estate planning attorney ensures that your strategies remain compliant and effective, safeguarding your legacy for future generations.