In an era where economic uncertainties and shifting financial landscapes have become the norm, the pursuit of financial independence is more relevant than ever, particularly for families seeking stability and security. Achieving financial independence as a family is not merely about accumulating wealth; it is about cultivating a sustainable lifestyle that aligns with shared goals and values. This analytical exploration delves into the strategic approaches and practical steps families can take to attain financial autonomy. By examining key principles such as budgeting, investing, and income diversification, we aim to empower families with the knowledge and confidence needed to navigate their unique financial journeys. Through careful planning and informed decision-making, financial independence can transition from a distant aspiration to an attainable reality for families across various socioeconomic backgrounds.
Building a Family Financial Plan that Lasts
Creating a sustainable financial strategy for your family involves more than just budgeting. It requires a comprehensive approach that aligns with your long-term goals and values. Start by evaluating your current financial status, considering income, expenses, and debt. Open communication with family members is crucial to understand everyone’s financial priorities and aspirations. Once you have a clear picture, you can begin to set realistic goals that everyone can work towards.
To ensure your plan is robust, incorporate these key elements:
- Emergency Fund: Aim to save at least three to six months’ worth of living expenses.
- Investment Strategy: Diversify investments to balance risk and growth potential.
- Insurance Coverage: Protect your family with adequate health, life, and property insurance.
- Debt Management: Prioritize paying off high-interest debts while maintaining regular payments on others.
- Regular Review: Schedule periodic reviews of your financial plan to adjust for changes in income, expenses, or goals.
By integrating these components into your family’s financial blueprint, you can cultivate a resilient plan that not only withstands economic fluctuations but also empowers your family to achieve financial independence.
Strategies for Diversifying Family Income Streams
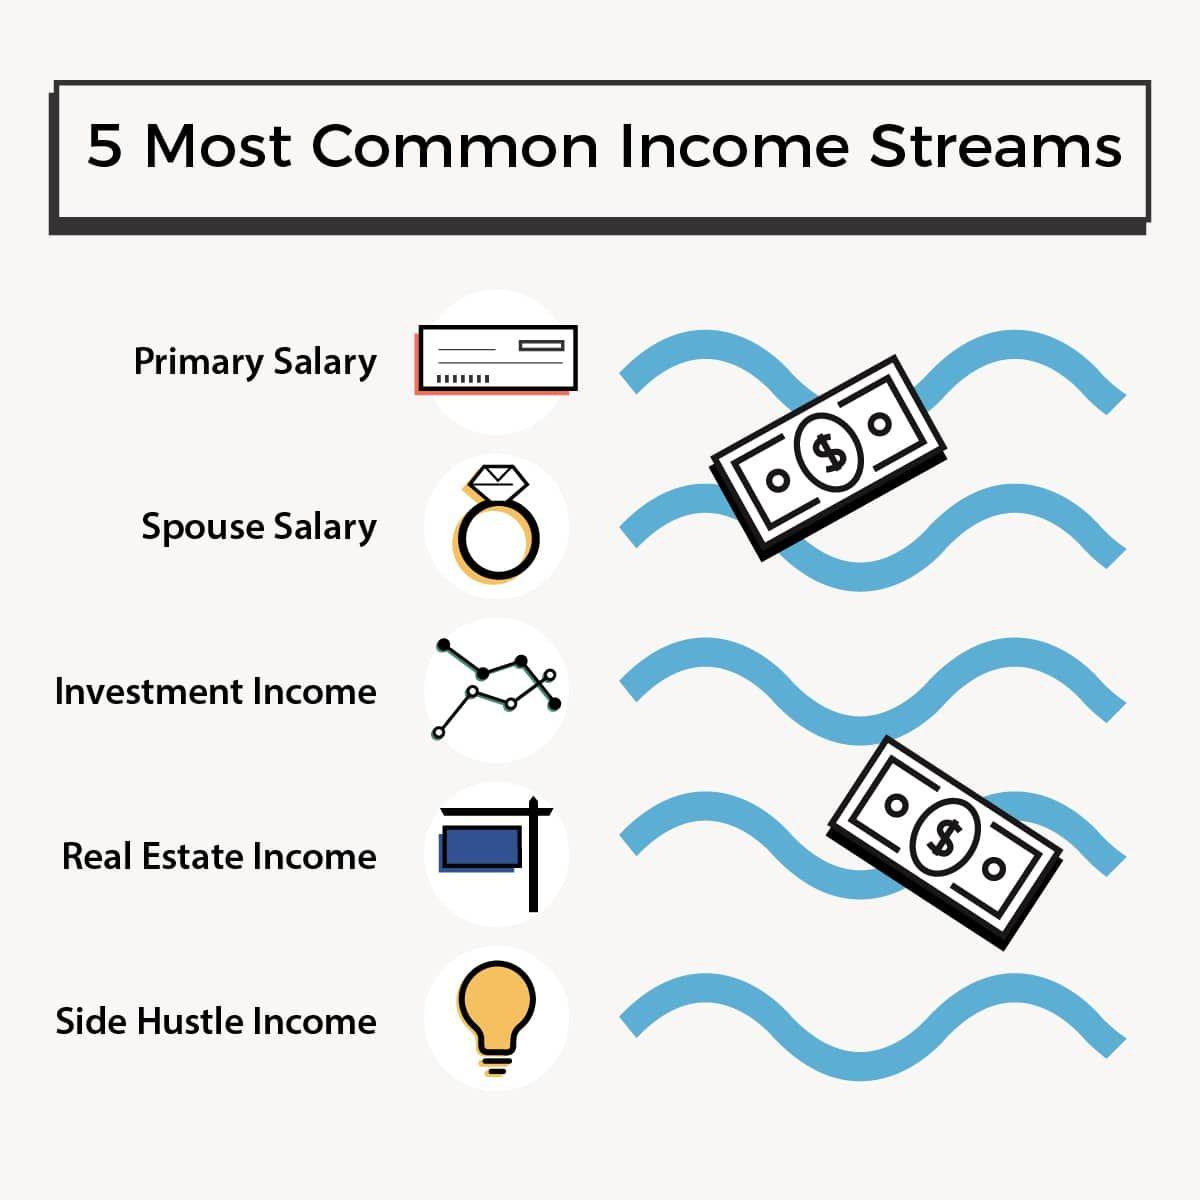
To foster financial independence, it’s crucial for families to explore various avenues that can generate additional income. One effective approach is to leverage existing skills and hobbies into side businesses or freelance work. For instance, a family member with a knack for photography could offer services for events or sell prints online. Meanwhile, someone skilled in web development might take on freelance projects during weekends. Harnessing personal talents not only brings in extra income but also allows for personal growth and job satisfaction.
- Invest in Rental Properties: Real estate can be a lucrative long-term investment. By purchasing rental properties, families can earn a steady stream of passive income while building equity.
- Explore Stock Market Opportunities: Engaging in stock market investments, whether through individual stocks, mutual funds, or ETFs, can diversify income sources and potentially yield substantial returns over time.
- Start an Online Store: E-commerce platforms offer the opportunity to sell products globally. This could range from handmade crafts to dropshipping, catering to various interests and expertise.
Implementing a mix of these strategies not only mitigates financial risk but also enhances the family’s overall economic resilience. By embracing a multifaceted approach, families can position themselves to achieve long-term financial independence.
Optimizing Family Expenses without Sacrificing Quality of Life
Balancing a family budget while maintaining a fulfilling lifestyle can be challenging, but with strategic planning, it’s entirely achievable. Start by evaluating your current spending habits and identifying areas where you can cut costs without impacting your family’s happiness. This might involve simple changes such as cooking at home more often or finding free community events instead of costly entertainment. It’s important to focus on value rather than just cost, ensuring that your choices enrich your family’s life.
Consider these practical strategies to optimize your expenses:
- Grocery Shopping: Plan meals ahead and make a list to avoid impulse purchases. Buying in bulk and choosing generic brands can also lead to significant savings.
- Utilities: Implement energy-saving practices, like using LED bulbs and unplugging electronics when not in use, to lower monthly bills.
- Transportation: Carpooling or using public transport can reduce fuel costs, while regular maintenance helps prevent expensive repairs.
- Insurance: Regularly review policies to ensure you’re not overpaying for coverage you no longer need.
By consciously making these adjustments, you can redirect funds towards experiences that truly matter to your family, such as vacations or educational activities, all while paving the way to financial independence.
Teaching Financial Literacy to Children for Long-Term Success
Instilling financial literacy in children is a cornerstone for nurturing a financially independent family. Understanding the value of money from a young age not only fosters a sense of responsibility but also equips them with essential skills for the future. Parents can start by introducing basic concepts like budgeting and saving through everyday activities. For instance, involve children in grocery shopping and discuss the cost of items, encouraging them to make choices based on a budget. This hands-on experience can be invaluable in teaching them about financial decision-making.
Moreover, creating an environment where open discussions about finances are encouraged can significantly enhance their understanding. Consider setting up a family meeting to discuss financial goals and strategies, making it an engaging and educational experience. Here are some practical steps to integrate financial literacy into daily life:
- Set up a Savings Jar: Encourage children to save a portion of their allowance or gift money. Watching their savings grow can be a powerful motivator.
- Introduce Basic Investment Concepts: Simplify investment ideas using examples, such as explaining how buying a toy today might mean not being able to buy another toy later.
- Use Technology: Leverage apps designed for kids to manage virtual allowances and track spending.
By embedding these practices into your family routine, you not only prepare your children for their financial future but also work towards achieving collective financial independence as a family.